Private Equity's Hard Year Has Real Openings
A war in the Gulf, an oil spike, a Fed that may raise rates, and an AI shock that took $285 billion out of software stocks in a day have all landed on sponsors in 2026. Capital is still flowing to the firms that return it, and the law has mostly moved their way.
Private equity has taken a beating in 2026. A war in the Persian Gulf, an oil-price spike, a Federal Reserve that may raise rates this month and an artificial-intelligence shock that wiped $285 billion off software stocks in a single session have hit sponsors almost simultaneously.
The industry isn’t broken. Capital is still flowing to firms that return cash to investors. The best assets are still finding buyers. Data centers have turned into a genuine profit center. And on balance, the law has moved in sponsors’ favor this year more often than against them. Here is where things stand, and where I see the value.
THE NUMBERS, YEAR TO DATE
US private equity firms invested $545.1 billion in the first half, on pace to match 2025’s $1.1 trillion, but across only 3,926 deals against 9,350 for all of last year, according to KPMG. Fewer deals, much larger checks.
The second quarter was the soft spot. PitchBook puts deal value at $177.3 billion, down 37.5% from the first quarter, with software deal value down 65.7% from a year earlier.
Exits are the real pressure point. US exit value reached $273.1 billion at midyear across 508 transactions, well below 2025’s pace of 1,376. Sponsor-to-sponsor sales fell to 94 in the second quarter, the fewest in at least a decade.
Fundraising is thin but alive. US sponsors raised $159.6 billion across 223 funds through June, roughly in line with 2025. Experienced managers took $139.3 billion of it; emerging managers took $20.3 billion. That is the pattern of the year. Concentration, not collapse.
TEN YEARS OF PERSPECTIVE
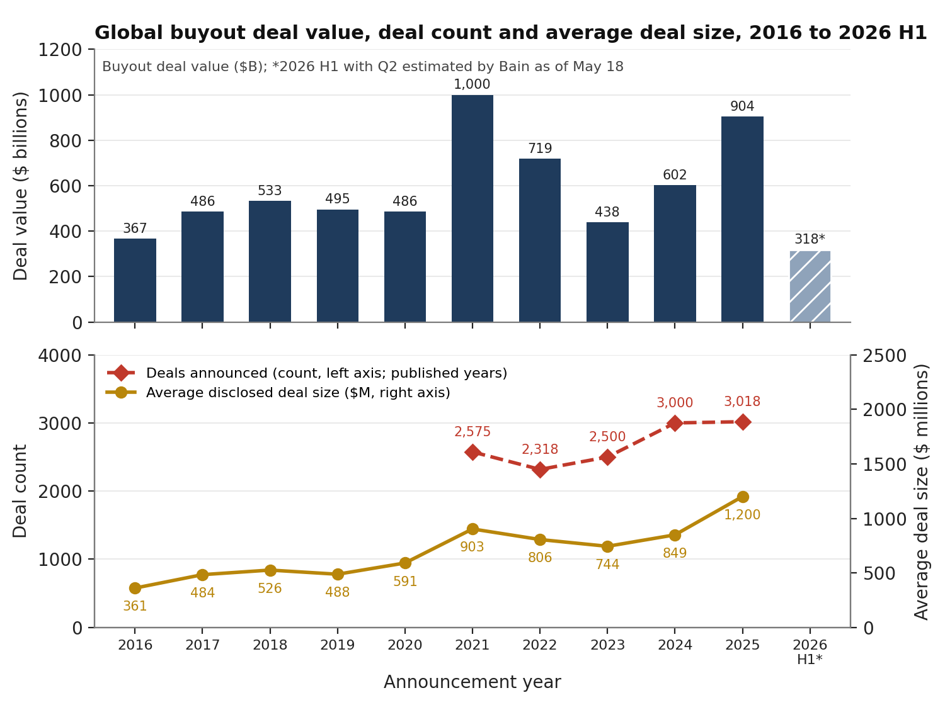
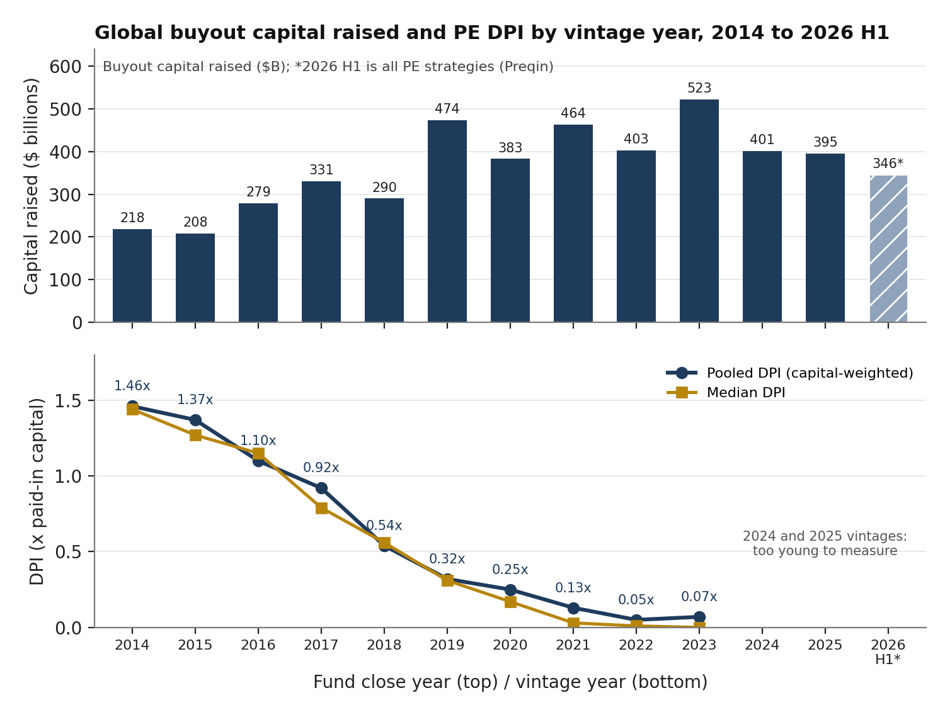
Two things stand out from the longer record. First, deployment recovered before fundraising did, and it recovered on size rather than count. Bain & Company reports global buyout deal value reached $904 billion in 2025, the second-best year on record, while fundraising fell 16 percent to $395 billion, a fourth straight annual decline. The current pace is drawing down dry powder that is not being replaced, because fundraising follows distributions, and distributions have been weak.
Second, the return problem is a cash problem, not a value problem. PitchBook’s global benchmarks show 2014 to 2017 vintages at a total value multiple near 2.0 times. But 2017 to 2021 vintages show distributions to paid-in capital, or DPI, below 1.0 times, and 2019 to 2021 vintages sit below 0.35 times. Investors are not asking whether the assets are good. They are asking when they get paid.
THE MACRO PICTURE
The conflict with Iran that began in late February shaped the year. Leveraged-loan issuance fell 22.5 percent in the first quarter. Brent crude touched $100 in July, and the two sides were exchanging strikes again in early September. The Fed held its target range at 3.5 to 3.75 percent in July on a 9-to-3 vote, and the market leans toward a quarter-point increase this month.
My read is that this is a shock rather than a new regime. Deals signed this fall should carry a rate cushion, and pipelines are worth keeping warm.
WHERE THE DEALS ARE
Energy and power are the clear winners. KPMG puts private equity investment in energy and natural resources at $90.2 billion through June, on pace for its best year in more than a decade. Legal services and health care roll-ups continue. Software is not closed, but it is selective. Thoma Bravo’s $4 billion insurtech take-private, and reported talks around Workday, show there is still demand for regulated, cash-generating vertical software.
AI DATA CENTERS: THE CLEAREST BRIGHT SPOT
Data centers are where sponsors have actually made money this year. S&P Global counted 113 transactions worth more than $69 billion in 2025, a record, led by the $40 billion sale of Aligned Data Centers, an exit for Macquarie. US data center deal activity hit a five-year high in 2025 and held through the first half of 2026. Blackstone’s digital infrastructure trust raised $1.75 billion in a May IPO. Debt markets now price contracted capacity like a utility. Hut 8’s Texas project sold $4.25 billion of notes in June at a 95 percent loan-to-cost ratio, fully pre-leased for 15 years to an investment-grade tenant, according to J.P. Morgan.
Three things separate a good deal from a bad one here: the tenant, the power and the demand assumption. Hyperscaler-leased assets trade at a premium. A site with secured power holds its value; a site waiting on a grid interconnect does not. And S&P’s own analysts note that hyperscalers are investing as though every one of them will still have a business in ten years, which is unlikely to be true. The underwriting that holds up is the lease and the power, not the AI story.
THE SAASPOCALYPSE
The biggest shock to technology private equity this year did not come from the Gulf. It came from Anthropic. On January 12 the company introduced Claude Cowork, an AI agent built to do professional work, and on January 30 it released open-source plugins for legal review, compliance, sales preparation and research, the tasks that sit at the center of high-margin subscription software. On February 3, roughly $285 billion of software, legal-tech and data-provider market value disappeared in one session. A Jefferies trader called it the SaaSpocalypse, and the name stuck. The S&P Software & Services Select Industry Index lost 25 percent between the Cowork launch and February 23. Claude Code had already cut the cost of building software. Cowork persuaded the market that the cost of using it would fall too.
For sponsors the exposure is direct. Software is the largest sector in most buyout portfolios, and the Bank for International Settlements puts private credit’s software loan book above $500 billion, or 19 percent of direct loans. Companies underwritten between 2018 and 2020, before generative AI, are the vintages most exposed. Software is not dead. Per-seat pricing is now negotiable, and proprietary data, regulatory position and embedded transaction flows are what hold value. PwC finds that firms using AI to lift portfolio margins are outperforming in both fundraising and exits. With multiple expansion gone, margin is the lever that remains.
Private credit had a scare, not a crisis. Three Blue Owl business development companies sold $1.4 billion of loans at 99.7 percent of par after the smallest of the three suspended redemptions. The price is the point. This was a liquidity mismatch, not a credit loss. Morgan Stanley sees defaults possibly reaching 8 percent, against a historical norm of 2 to 2.5 percent, and calls that significant rather than systemic. For sponsors with clean credits, terms are still available.
EXITS AND FUNDRAISING
The IPO window is open. PwC counts roughly $114 billion raised in traditional IPOs through June, seven times the prior year’s pace. The line is long, though. CBIZ estimates more than 13,500 US companies sit in sponsor portfolios, nearly a third of them older than six years, and clearing that backlog at the current pace would take about nine years. A sponsor holding a genuinely good asset is usually better off selling it. Waiting tends to cost more than the discount.
DPI has replaced IRR as the number limited partners care about. Through early 2026, firms with strong distributions raised new funds quickly; others did not. About 70 percent of fund series expected back in market have returned, and Bain expects the long-run failure rate to resemble the financial crisis, around 20 percent. LPs have consolidated behind managers with distribution records and scale, and fees are compressing; the average buyout fee was 1.6 percent in 2025. Scale and specialization are the two ways through.
THE LAW: WHAT CHANGED, AND WHAT IT MEANS
The legal story of 2026 will outlast the oil price. Seven developments matter, roughly in order of importance to a sponsor.
- Retirement capital. On March 30 the Labor Department proposed a rule giving 401(k) fiduciaries broad discretion to include private equity, provided they follow a prudent process. The Supreme Court hears Anderson v. Intel this fall, on whether participants suing over private assets in target-date funds must plead a meaningful benchmark; the Labor Department has sided with Intel. A favorable rule and a favorable decision by mid-2027 both look likely. The price of entry is a product built for defined-contribution plans: frequent NAV, no capital calls, real liquidity, ERISA-grade fee disclosure and independent valuation. The firms that finish that build first will have a distribution channel their competitors do not.
- The SEC. The 2023 private fund adviser rules were vacated by the Fifth Circuit in 2024 and have not been revived. The commission’s agenda now favors retail access through registered funds and looser limits on performance fees; that proposal reached the White House budget office on August 31. Sponsors would still be wise to draft as if the vacated rules applied, because LPs keep asking for the fairness opinions and disclosures those rules would have required.
- Antitrust. A federal court in Texas threw out the FTC’s expanded merger filing form in February, and the Fifth Circuit declined to stay that ruling in March, so filers are back on the pre-2025 form. States are moving the other way. California will require a copy of every federal filing from 2027, and more than a dozen states now review health care deals below the federal threshold, several naming private equity specifically. A health care roll-up in a notice state needs 90 to 150 days built into the timeline.
- Delaware. In Rutledge v. Clearway, decided February 27, the Delaware Supreme Court upheld the 2025 statute that gives controlling stockholders a safe harbor, committee approval or a majority-of-the-minority vote, for most controller transactions. For a sponsor with a control stake in a public company, it is the most useful decision in a decade, and a Section 144 committee belongs in the playbook.
- Credit documents. The Serta and Mitel rulings, one against an uptier exchange and one for it, turned on the exact wording of each credit agreement. Lenders now negotiate express blockers and sign cooperation agreements before a borrower can divide them. The room for coercive exchanges has narrowed.
- Tax. Last year’s US tax law left carried interest alone, restored the EBITDA-based interest deduction and made bonus depreciation permanent. The UK went the other way. From April 6, carry is taxed as income, at an effective rate of about 34.1 percent for qualifying carry with a 40-month average holding period, up from 32 percent. Fund design in London now turns on holding period.
- Europe. AIFMD II took effect in April with new rules for loan-originating funds and new liquidity requirements for open-ended funds, both of which reach the semi-liquid vehicles sponsors are building for private wealth.
BOTTOM LINE
Bain calls the new deal math “12 is the new 5.” A 2015-vintage buyout needed about 5 percent annual EBITDA growth to return 2.5 times capital; today’s leverage and multiples require closer to 10 to 12 percent. That is harder. It is also honest. The easy-money years were the anomaly.
The sponsors that do well from here will sell good assets rather than hold them out for a better mark, grow earnings rather than wait for multiples, know their software exposure by vintage, own contracted data center capacity with secured power, and have a defined-contribution product already in design.
Five things are worth watching this fall: the Fed’s path after the September meeting, any settlement over the Strait of Hormuz, the text of the SEC’s retail-access proposal, oral argument in Anderson v. Intel, and whether third-quarter exit data shows the IPO window reaching sponsor-backed companies. My guess is that at least three of the five break the right way.
Louis Lehot is a Silicon Valley growth equity and private equity lawyer and a partner at Foley & Lardner LLP. He advises technology, life sciences and clean energy companies, their boards and their investors on growth equity investments, buyouts, take-privates and exits. He is ranked by Chambers USA and The Legal 500, is listed in Super Lawyers, is a JD Supra Readers’ Choice Award recipient, and serves on the Law360 M&A Editorial Advisory Board, the NACD Northern California Leadership Council and the faculty of the Stanford Directors’ College.
Special thanks to Bella Tappin for editing assistance.