The Growth Docket Vol. I, No. 4 – New Leaders, New Prices, Higher Rates
Control capital for growth. Where venture ends and buyouts begin.
Friends,
Joe Baratta leaves Blackstone at year-end, and Blackstone will not replace him. Hernan Cristerna, JPMorgan’s longtime M&A chief, retires the same week. The generation that built modern private equity is handing over the keys. Growth equity is doing the same, with less press. Here is the week.
When a Fund Changes Generations
Many of the firms that built growth equity were founded in the 1980s and 1990s. Their founders are passing the firm to a second generation, or should be. Only about 6 percent of fund leaders turn over in any five years, against more than half of public company CEOs. Fewer than half of managers have a written succession plan. And 96 percent of the investors who back them say it matters at re-up.
The handoff turns on four things. Carry and ownership of the management company have to move down over several funds, or the best young partners leave and raise their own. The key person clause has to name the people actually doing the deals. The founders have to hand over the relationships while they can still make the calls. And some founders sell a minority stake in the firm to pay for the transition.
If you run a portfolio company, read your documents. Board seats, consent rights, observer rights and side letters often name a person, not a role. Find out who covers you before the next board meeting, and get it in writing. If you are choosing a growth investor, ask one more question: who will sit on my board in five years?
Buy, Sell or Wait: The Seller’s Side
Last week covered what buyers want. The panel recap has a second half for the people selling.
🔹 Pitch the buyer’s return, not the sector multiple. Most funds need about 25 percent a year. Show them how they get it with you.
🔹 Split the price if you have to. Holders who want out can sell at a discount. Holders who roll can share the upside above the buyer’s target.
🔹 Buy cyber coverage before the data room opens. Deal insurance now carves out AI and cyber risk, and the seller ends up holding it through a separate indemnity.
🔹 CFOs, negotiate your own deal before signing. Change-of-control terms and your transition role are worth the most before the merger agreement is signed.
Rob Bartlett’s October numbers at Jefferies show what is at stake. Software growing 20 to 30 percent trades at 11.5 times next year’s revenue. Growing 10 to 20 percent, 5.5 times.
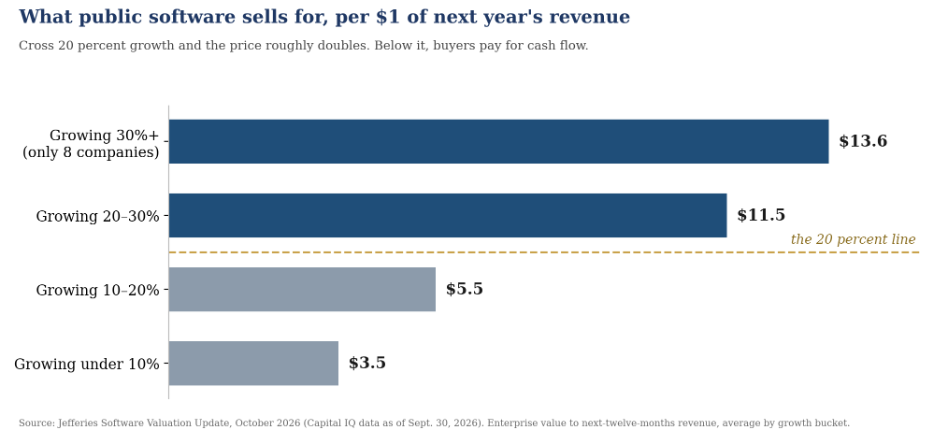
The surprise is vertical software, the industry-specific products growth investors have long treated as safe. It fell to 4.6 times revenue in September, down 36 percent in a year and below its own five-year average. The market now prices it as exposed to AI.
Two Nights of SF Tech Week
Ready for Anything. Thanks to Ellie Yashiro of SVB and to Open Future Forum for Tuesday’s panel on IPOs, SPACs and capital market shifts. What stuck: the IPO window is a cohort, and each deal has to trade well for the next one to get out. Staying private is not free when employees want liquidity and private money costs this much. Build for an IPO and a sale at the same time, with public-company controls, an audit firm that can sign a registration statement and a clean cap table. A SPAC still works only with a strong sponsor, committed money behind it and a company that could stand on its own. And AI companies will be judged on the old metrics in the end: durable revenue, margins after compute, cash.
Sidebar Summit. Monday’s opener, which Foley sponsored, was a fireside chat with Venky Ganesan of Menlo Ventures on whether this is 1999. His frame is Max Bazerman’s $20 auction: bidders keep going past the prize because quitting locks in the loss. That is the best explanation going for why no one is slowing down on AI spending. Thanks to Vishal Verma.
On Our Desk
🔹 Kapital, $125 million. We represented Kapital, an AI-driven business lender in Latin America, Spain and the US, in an equity and debt raise led by Tru Arrow Partners. Announcement.
🔹 Iron Path Capital Fund II, $450 million. We advised on an oversubscribed specialty industrials and healthcare fund, raised in five months. Announcement.
🔹 EMS and AMD Supply. We represented EMS, a Wynnchurch Capital portfolio company, in an add-on. Announcement.
The Loan Desk: The Fed Is Not Done
October is probably off. September added only 29,000 jobs, unemployment rose to 4.2 percent and core PCE inflation eased to 3.0 percent. Futures give an October 28 hike about a one-in-four chance.
December is a different story. Sixteen of 18 Fed officials projected another increase this year, futures price one in December as likely, and the officials’ median holds the rate near 4.1 percent through 2027, with no cut before 2028. Meanwhile the 10-year hit 5.35 percent on Monday, its highest since 2002.
For a deal team: assume one more quarter point on floating-rate debt and no relief for a year. Negotiate outside dates, financing conditions and ticking fees like they matter, because they do. And expect investors to ask why they should lock up money for five years when the 10-year pays over 5 percent.
From My Desk
🔹 An Early Look at Q3 2026 PE Activity, with Andre Thiollier. US deal value up 20 percent to $230 billion, exits up 51 percent to $165 billion. Fundraising is the soft spot: funds closed down 31.5 percent, dollars down 10 percent.
🔹 Record Startup Shutdowns Reflect a Market That Is Moving Forward.
🔹 What Is a General Counsel Worth?, from our GC compensation lunch, ahead of the next one on October 30.
🔹 In the Daily Journal’s Capital & Counsel on the IPO market: “The window is open for the largest companies and closed for the rest.”
On the Calendar
LP/GP Event with Jersey Finance, Monday, October 12, Foley San Francisco. Reply for a seat.
Investors on the Bay, a Fall Mixer, Friday, October 23, San Francisco. Register.
One Way Ventures Summit, Wednesday, October 28, San Francisco. Register.
General Counsel Executive Forum, Private Lunch, Friday, October 30, San Francisco. In-house counsel only. Request a seat.
IPO Readiness, Wednesday, November 18, San Francisco, with SVB, Protiviti and Heffernan. Reply for a seat.
2027 Outlook, Friday, December 11. Reply for a seat.
Closing Argument
🔹 Portfolio CEOs: if your fund is changing generations, know who covers you.
🔹 Sellers: pitch the buyer’s return. Buy the cyber policy first.
🔹 Deal teams: one more hike, no cuts before 2028. Read the rate mechanics.
Funds change leaders. Markets change prices. The companies that are ready get to choose.
— Louis
Standard disclosures: opinions my own, not my firm’s. Not legal advice. Attorney advertising. Prior results do not guarantee future performance. This newsletter is built the way I believe modern legal work should be done. I use AI for productivity and efficiency in research and drafting. The ideas are mine, the voice is mine, the edits are mine, I check the facts, and I own every word. Foley & Lardner LLP represents sponsors, lenders and companies, some of which may be active in the matters discussed. Software market data from Jefferies’ monthly software valuation update, compiled from Capital IQ as of Sept. 30, 2026, used with permission. Rate and inflation data from the Bureau of Labor Statistics, the Bureau of Economic Analysis and the Federal Reserve.